Gordon Blair Financial Services Insights

Green Mortgages & EPC Ratings: Could an Energy-Efficient Home Help You Save?

Energy efficiency is becoming an increasingly important part of the UK mortgage market. For some buyers and homeowners, a qualifying EPC rating could open the door to green mortgage products offering preferential rates, cashback or incentives towards eligible home improvements.

Whether you are buying, remortgaging or planning improvements such as insulation, solar panels or a heat pump, understanding how green mortgage products work could help you identify options that may not be available through a standard mortgage alone.

Green Mortgages Explore mortgage products linked to energy-efficient homes
EPC Ratings Understand why your property's energy rating may matter
Incentives Potential preferential rates, cashback and lender support
Home Improvements Finance options for insulation, solar panels and heat pumps

Green Mortgage Advice

Could your EPC rating affect your mortgage options?

Most homeowners think of an Energy Performance Certificate as a measure of energy efficiency and running costs. Increasingly, however, EPC ratings can also be relevant when comparing certain mortgage products.

A growing number of lenders offer green mortgage products or incentives for properties that meet specific energy-efficiency criteria. Depending on the lender, this may include reduced mortgage rates, cashback for purchasing or remortgaging an eligible property, or financial support towards qualifying energy-efficient improvements.

This does not mean that a higher EPC rating automatically guarantees a cheaper mortgage. Your eligibility will still depend on the lender's criteria and your individual circumstances, including affordability, income, deposit or equity, property value, credit history and the mortgage product selected.

The key point is that energy efficiency is becoming another factor worth considering when reviewing your mortgage options.

Understanding Green Mortgages

What is a green mortgage?

A green mortgage is generally a mortgage product that offers a benefit or incentive when a property meets specified energy-efficiency requirements.

Different lenders set different criteria. Some products are designed for buyers purchasing energy-efficient homes, while others may be available to existing homeowners remortgaging a property with a qualifying EPC rating.

Certain lender schemes may also support homeowners who want to improve the energy efficiency of their property. Depending on the product, this could include cashback or other incentives connected with eligible improvements.

Green mortgage eligibility can vary considerably, so it is important to look at the whole mortgage rather than focusing on a single headline benefit. Interest rates, fees, cashback, repayment terms and overall cost should all be considered together.

Potential Green Mortgage Benefits

What could a green mortgage offer?

The exact benefits vary by lender and product, but qualifying borrowers may find a range of incentives designed around energy-efficient homes and greener improvements.

01

Preferential mortgage rates

Some lenders may offer a reduced or preferential mortgage rate when a property meets specific EPC or energy-efficiency requirements.

02

Cashback on eligible homes

Certain green mortgage products may offer cashback when purchasing or remortgaging a qualifying energy-efficient property.

03

Green home improvement incentives

Depending on the lender and scheme, incentives may be available towards qualifying energy-efficiency improvements, with some offers providing up to £2,000 cashback.

04

Support for sustainable improvements

Eligible improvements may include insulation, solar panels, heat pumps or other measures designed to improve a property's energy performance.

Gordon Blair Financial Services Insight

A green mortgage should still be judged as a mortgage first. A cashback incentive or preferential green rate can be attractive, but the most suitable option will depend on the full cost of the product, your circumstances and the lender's eligibility criteria.

Buying & Remortgaging

When could a green mortgage be relevant?

Green mortgage products may be relevant at several different stages of home ownership.

Buying an energy-efficient home

If you are purchasing a property with a qualifying EPC rating, certain lenders may offer green mortgage products with preferential pricing or cashback. It can be worth checking the EPC before choosing your mortgage.

Remortgaging your existing property

If you already own an energy-efficient home, or have improved its energy performance, you may find green remortgage products worth comparing when your existing deal ends.

Planning home improvements

If you are considering insulation, solar panels, a heat pump or other energy-efficiency measures, some mortgage products or lender incentives may help towards eligible improvements.

Reviewing your EPC rating

Your property's current EPC may influence whether it meets a lender's green criteria, making it useful information to have when discussing your mortgage options.

Celebrating Our Team

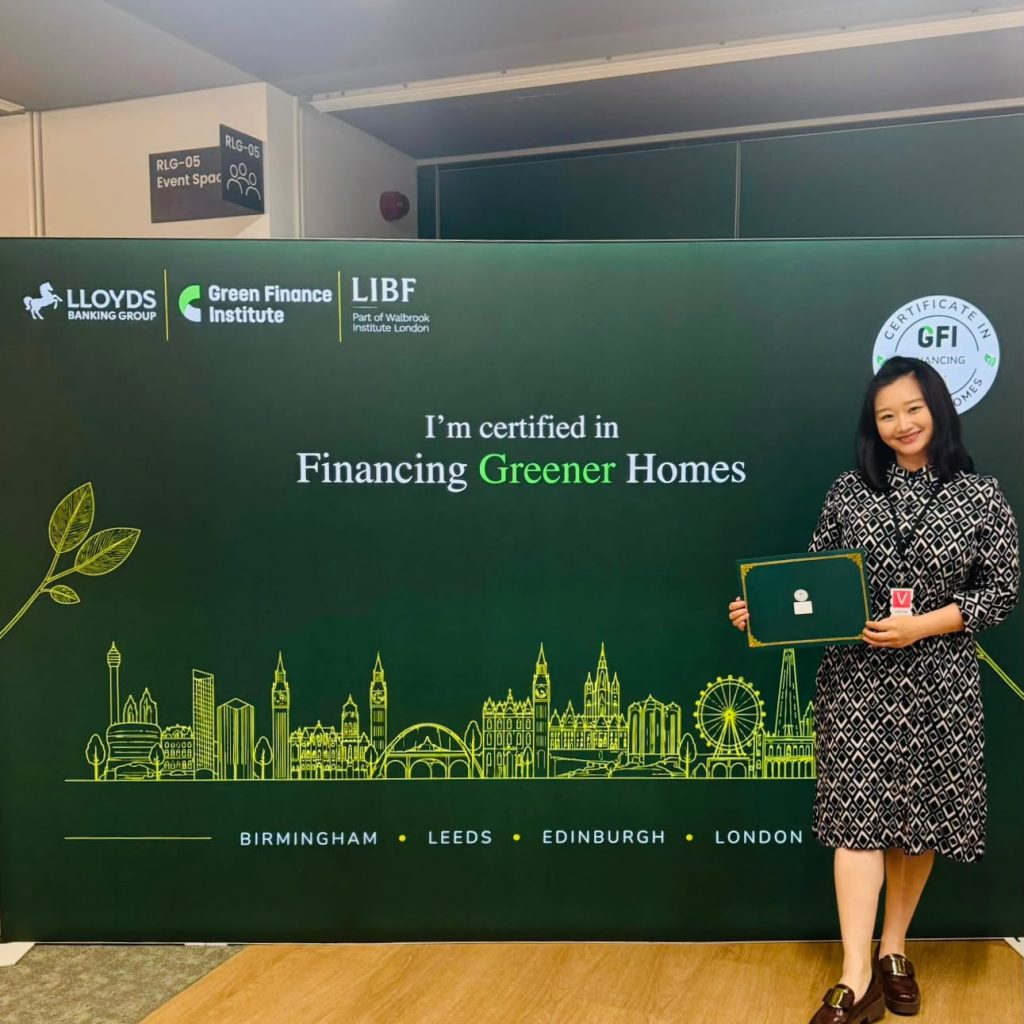
Jessica achieves her Green Mortgage Certificate

We are delighted to congratulate Jessica, one of our Mortgage Advisers, on achieving her Green Mortgage Certificate with Lloyds Banking Group and the London Institute of Banking & Finance (LIBF).

Meet Jessica Qi & view her adviser profile →

What This Means for Our Clients

Building specialist knowledge as the mortgage market evolves

As green mortgages become more prominent, understanding energy-efficient properties, lender criteria and sustainable home improvements is becoming increasingly valuable for mortgage advisers.

  • Green mortgage products for qualifying energy-efficient homes
  • Potential preferential mortgage rates
  • Cashback and incentives linked to eligible properties
  • Green home improvement incentives and finance options
  • The potential relevance of EPC ratings when buying or remortgaging
  • Mortgage options connected with sustainable home improvements

Before You Choose

Five questions to ask when considering a green mortgage

Looking beyond the headline incentive can help you understand whether a green mortgage is genuinely competitive for your circumstances.

01

Does my property meet the EPC criteria?

Green mortgage eligibility often depends on the property's energy-efficiency rating or other lender-specific requirements.

02

Is the green rate actually competitive?

Compare the interest rate, fees, cashback and overall cost with suitable standard mortgage products.

03

Could I qualify for cashback?

Cashback may be available for eligible purchases, remortgages or qualifying green home improvements, depending on the lender.

04

Are planned improvements eligible?

Check whether work such as insulation, solar panels or heat pumps meets the lender's current scheme requirements.

05

What is the overall cost of the mortgage?

A green incentive should be considered alongside the full mortgage cost and your longer-term plans.

Gordon Blair Financial Services

Could a green mortgage be right for you?

Whether you are buying, remortgaging or planning energy-efficient home improvements, Gordon Blair Financial Services can discuss your circumstances and help you explore the mortgage options that may be available.

Talk to Our Adviser →

Frequently Asked Questions

Green Mortgage FAQs

Some common questions buyers and homeowners ask about green mortgages and EPC ratings.

What is a green mortgage?

A green mortgage is generally a mortgage product offering a benefit or incentive when a property meets specified energy-efficiency criteria. Requirements and benefits vary between lenders.

What EPC rating do I need for a green mortgage?

There is no single EPC requirement across the market. Each lender sets its own eligibility criteria, so the rating needed will depend on the product selected.

Can a green mortgage offer a lower interest rate?

Some lenders may offer preferential rates for qualifying energy-efficient properties. However, rates and eligibility vary, and the overall mortgage cost should always be compared.

Can I get cashback with a green mortgage?

Potentially. Some lenders offer cashback on qualifying purchases or remortgages, while other schemes may provide incentives towards eligible green home improvements.

Can green mortgage incentives help pay for home improvements?

Some lender schemes may provide incentives for qualifying improvements such as insulation, solar panels or heat pumps. The amount available and eligible works depend on the lender.

Can I get a green mortgage when remortgaging?

Potentially. Certain lenders offer green remortgage products for properties that meet their energy-efficiency criteria.

Is a green mortgage always cheaper?

No. A green mortgage may include attractive incentives, but it is important to compare interest rates, fees, cashback, product terms and overall cost with other suitable options.

Can a mortgage adviser help me compare green mortgage products?

Yes. A mortgage adviser can review your circumstances, property details and EPC rating before helping you compare suitable mortgage options available through the lenders they work with.

Mortgage products, rates, cashback and green mortgage incentives are subject to lender criteria, eligibility and availability and may change or be withdrawn. Your home may be repossessed if you do not keep up repayments on your mortgage.

Our Offices:

Open in Google Maps
Shopping Basket